
You have packed your entire home into boxes, loaded everything onto a truck, and sent it down the highway. Now ask yourself – what happens if something breaks? What if a box is crushed, a table leg snaps, or an entire crate arrives water-damaged?
Most people assume their belongings are “insured” during a move. The reality is more complicated. Moving companies do not carry traditional insurance on your items. They offer liability coverage – and there is more than one level. Understanding the difference before you sign the paperwork can save you thousands if something goes wrong.
Valuation Coverage vs Insurance
What moving companies provide is valuation coverage – a level of liability they assume for your belongings during transport. True insurance is a product from a third-party insurer. The distinction matters because valuation coverage has limits, exclusions, and claim processes that differ from a standard insurance policy.
Federal law requires interstate movers to offer two levels of valuation coverage. When booking a residential move, you choose between them before anything gets loaded onto the truck.
Released Value Protection – The Minimum
Released value protection is included in every interstate move at no additional charge. Under this option, the company’s liability is limited to $0.60 per pound per article. A 50-pound flat-screen TV worth $1,200 would be covered at $30. A 10-pound vase worth $500 would be covered at $6.
This is not designed to make you whole. It exists as a baseline federal requirement. For anyone moving items of real value, released value protection is almost never enough.
Full-Value Protection – The Upgrade Worth Considering
Under full-value protection, the mover is liable for the replacement value of lost or damaged items, or the cost to repair them.
If an item is destroyed, the mover must replace it with a similar item or pay current market value. If it can be repaired, the mover can choose to repair it at their cost. You set a declared value for your shipment – most companies use a floor based on shipment weight (for example, $6.00 per pound times total weight).
Full-value protection typically costs 1-2% of the declared value. For a household with $50,000 in declared value, that might run $500-$1,000. That is a fraction of what you would lose replacing a damaged couch, broken TV, and scratched dining table out of pocket under released value.
What Full-Value Protection Does Not Cover
Even with full-value protection, there are exclusions.
Items you packed yourself are generally not covered – the mover loaded and transported what you gave them. Items of extraordinary value (typically defined as single items worth more than $100 per pound) must be declared on the inventory before the move or they may not be covered at full value. Pre-existing damage is excluded. Internal or mechanical damage to electronics with no visible external damage is difficult to claim. And catastrophic events like floods or earthquakes are typically excluded.
Third-Party Moving Insurance
If the mover’s valuation coverage is not enough, third-party moving insurance is available from independent insurers. These policies work like traditional insurance – you purchase before the move, declare your inventory and values, and file claims directly with the insurer.
Third-party policies often cover scenarios that valuation does not, including items you packed yourself, pairs and sets, water damage, and catastrophic loss. For a long-distance move with high-value items, a third-party policy adds meaningful protection on top of whatever the mover offers.
How to File a Claim
If something is damaged or missing, document everything at delivery. Note any visible damage on the delivery receipt before signing. Take time-stamped photos of damaged items and boxes. File the claim in writing using the mover’s claims form – interstate companies have 30 days to acknowledge and 120 days to make a settlement offer. Include photos, the original inventory list, the delivery receipt with your notes, and any receipts or appraisals.
If the company denies your claim or offers an unfair settlement, you can file a complaint with the FMCSA for interstate moves or your state’s attorney general for local moves.
Reduce the Risk Before It Happens
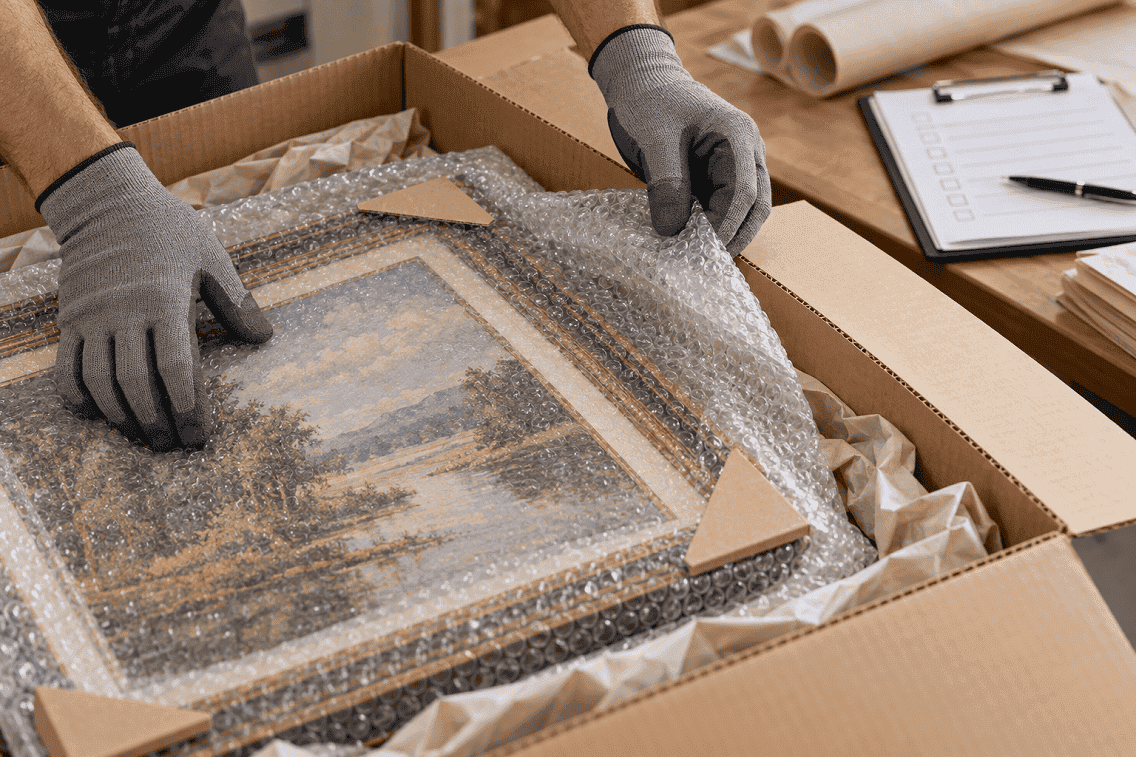
Coverage is your safety net, but prevention beats a claim. Use professional packing for fragile and high-value items – a properly packed dish set is far less likely to break. For irreplaceable pieces, custom crating provides the highest level of physical protection. Declare everything valuable on the inventory so it is handled accordingly. Take a pre-move photo inventory of major items. And never put irreplaceable items on the truck – family photos, legal documents, jewelry, and medication should travel with you.
Know What You Are Covered for Before the Truck Leaves
Moving coverage is not something to figure out after a box arrives crushed. The time to understand your options is before you sign the estimate – when you can still choose the right level of protection.
Central Van Lines walks every customer through their valuation options during the quoting process. Request a free estimate and we will make sure you know exactly what is covered before a single box hits the truck.